An investor signs a contract, the option period is short, and the closing clock starts moving before the renovation plan is fully settled. That is where short term financing advantages matter most, because the right structure can bring speed, flexibility, bridge a timing gap, and preserve capital for the work that comes next. For real estate investors, the benefit is not just getting money faster, it is matching funding to the deal stage so the purchase, rehab, and exit all stay connected. This list breaks down eight practical advantages, with trade-offs, examples, and what to check before the loan is signed.
Quick Lending is one Houston-area lending partner that works with investors on short-term, asset-based financing, subject to review and approval. Terms vary by property, borrower, and project, so the key question is not whether short-term funding is always the answer. The better question is whether it fits the timeline, the property condition, and the exit.
Table of Contents
- 1. Speed to Close in Time-Sensitive Transactions
- 2. Financing Properties That Need Work
- 3. Purchase and Rehab Funding in One Structure
- 4. Bridge and Transitional Financing
- 5. Flexibility Through Asset-Based Underwriting
- 6. Local Market Knowledge and Responsive Communication
- 7. Preserving Working Capital for Additional Projects
- 8. Clear Exit-Based Planning and Defined Project Structure
- Short-Term Financing Advantages: 8-Point Comparison
- Turning Short Term Financing Into a Clear Plan
1. Speed to Close in Time-Sensitive Transactions
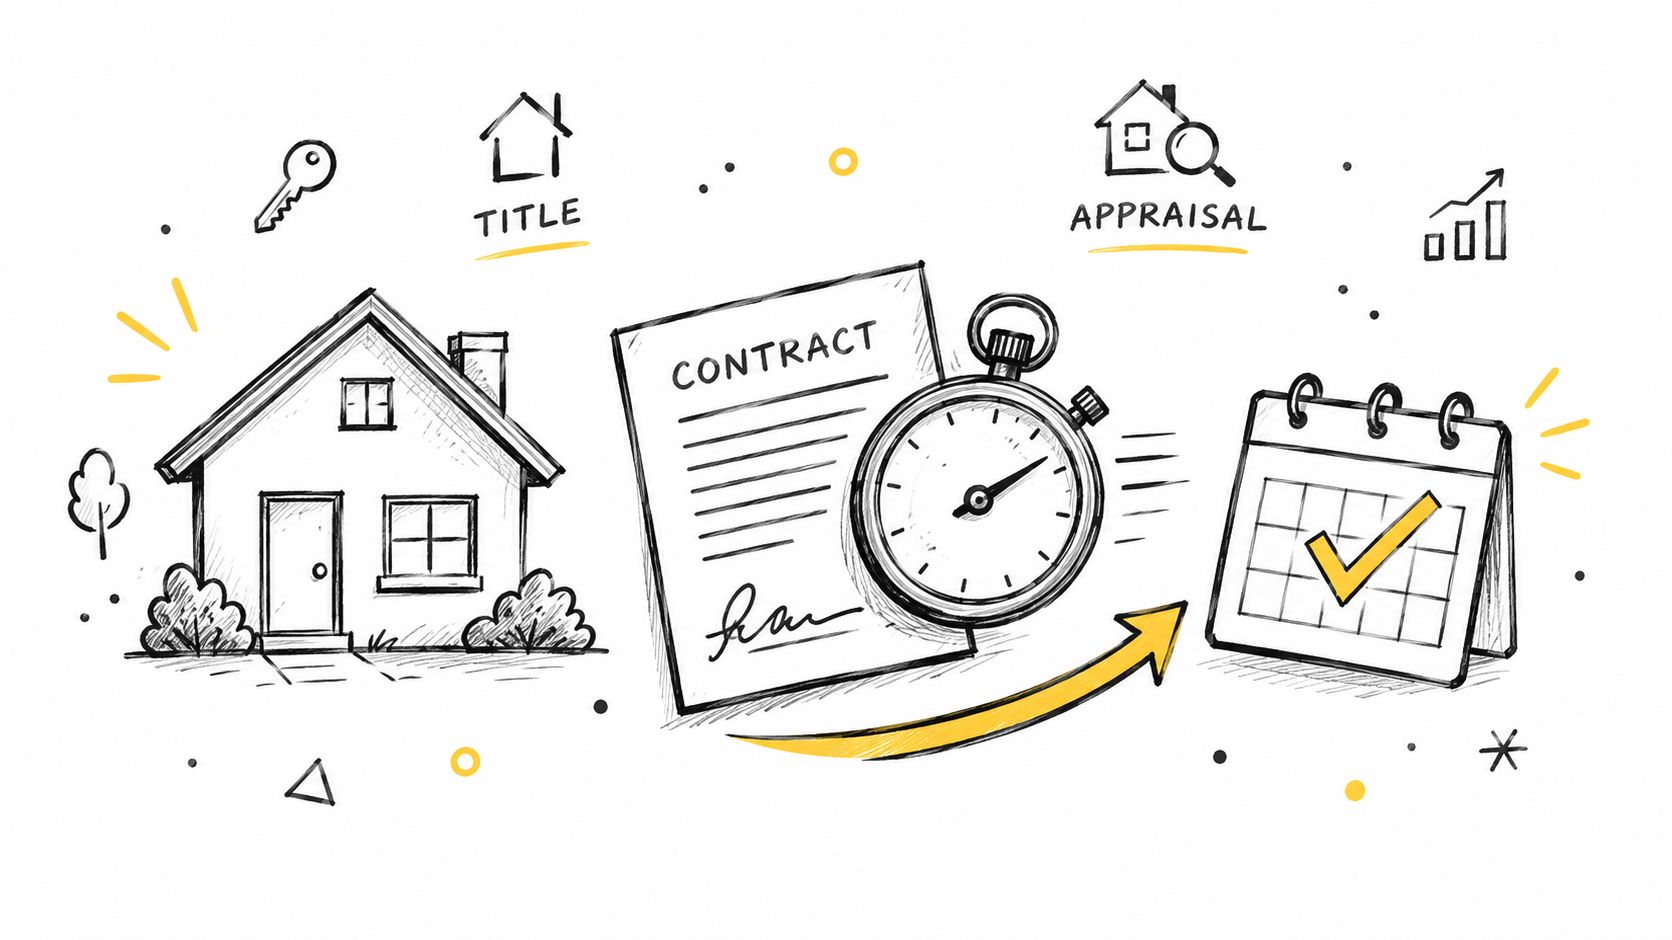
Speed is often the first reason an investor looks at short-term funding. A cash-style offer can close faster than a mortgage-financed purchase, and a 2024 peer-reviewed housing study found that cash purchases closed in 23.4 days on average, compared with 34.6 days for mortgage-financed purchases, a difference of 11.2 days or about 29% shorter time to close. The same study found sellers accepted $506,315 for cash transactions versus $528,050 for mortgage transactions, an average discount of $21,735, or about 4.1%, for the faster and more certain offer. That's a strong signal that speed can create real negotiating advantage when financing risk is part of the seller's decision source study.
What speed looks like on a real deal
An investor bidding at a county foreclosure auction needs funds ready on a fixed date. A short-term loan can make that possible when a conventional mortgage workflow would take too long. The same logic applies to a wholesaler under contract with a tight option period, where a missed deadline can kill the deal.
Practical rule: The clock matters as much as the rate. If the closing date is fixed, funding that arrives too late is effectively useless.
To make speed work, the borrower should have the contract, property details, and scope of work organized before applying. It also helps to ask the lender for the document list early, confirm the title company timeline, and build in a few extra days when possible. Quick Lending's intake process is designed around investor timelines, but closing still depends on title work, documentation, and review, so no specific closing time can be promised.
2. Financing Properties That Need Work
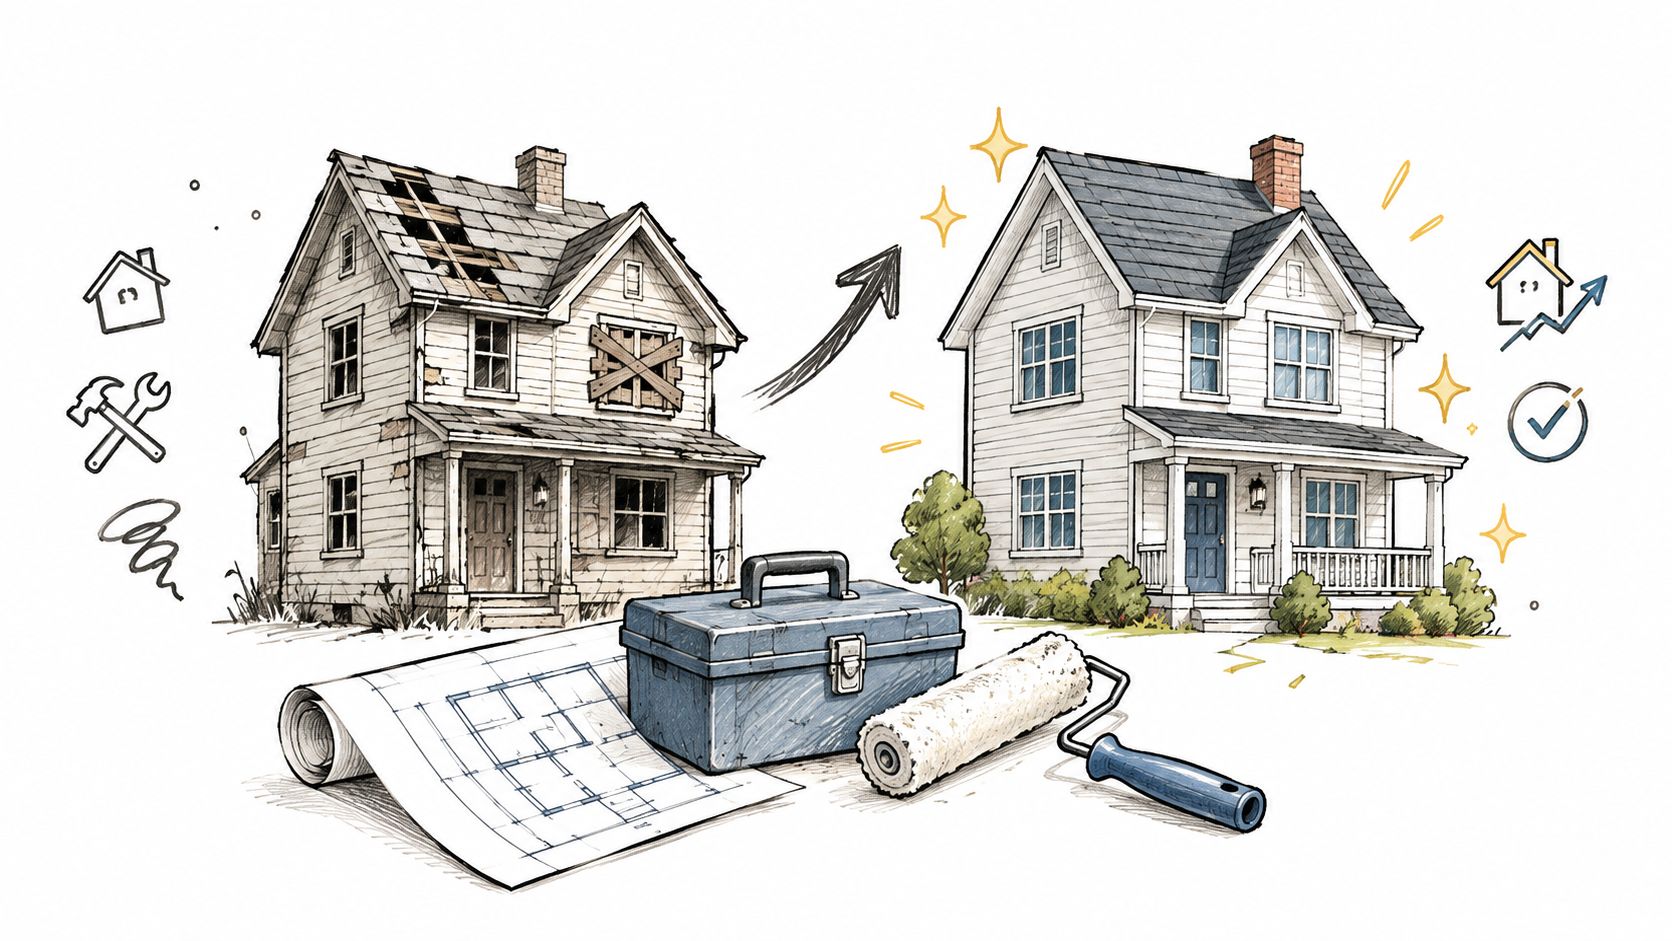
Many investors run into deals that a bank won't touch in their current condition. The property may be vacant, fire-damaged, missing major systems, or otherwise below conventional standards. Short-term asset-based financing can make those acquisitions possible by focusing on the property's potential after improvement instead of only its present condition.
Turning a distressed asset into a financeable one
Fannie Mae describes renovation financing as a way to repair, renovate, and update homes and rental properties, and notes that HomeStyle Renovation supports major repairs and structural renovations Fannie Mae renovation financing. For an investor, the key advantage is sequencing. The acquisition capital gets the property into the portfolio, then the rehab work moves it toward a sale or refinance.
A builder might buy a fire-damaged single-family home that a bank would reject in its current condition, complete the repairs, and then list it for sale. Another investor may pick up a vacant property with a failing roof and outdated electrical system, then refinance once the house is rent-ready. Quick Lending's acquisition funding is intended for distressed or non-bankable properties that need repairs or repositioning, subject to review and approval.
A useful prep list includes:
- Two contractor bids: Compare scope and pricing before the loan is finalized.
- A rehab contingency: Build a cushion into the budget for overruns.
- After-repair value support: Use local comparables, not wishful pricing.
- Exit feasibility: Confirm what must be fixed before the property can be insured or appraised for takeout financing.
A short-term loan can open the door to a property that wouldn't qualify today, but the exit still has to make sense after the work is done.
How to apply for a renovation loan can be a helpful starting point for investors planning that kind of acquisition.
3. Purchase and Rehab Funding in One Structure
Fix-and-flip projects usually have two major funding needs, the purchase and the renovation. When those are split across separate financing sources, the deal can become harder to manage. A purchase-and-rehab structure brings both pieces into one plan, which gives the investor a cleaner path from acquisition to resale.
Why one structure helps the budget stay honest
A single loan can make it easier to track the project from start to finish. The investor knows what the purchase costs, what the rehab budget looks like, and how the timeline should unfold. That does not remove risk, but it does create a clearer framework for decision-making.
A flipper buying a dated three-bedroom home may need a kitchen update, bathroom work, and new flooring. A small developer renovating a duplex can use the same kind of structure to keep costs aligned with the construction schedule. Quick Lending offers purchase and rehab financing for fix-and-flip projects, with disbursement details depending on the loan and project.
Before signing, the borrower should ask how rehab funds are released, whether draws are required, and what paperwork is needed for each release. That matters because even a good loan can create headaches if the disbursement process doesn't match how contractors work.
Practical rule: The headline terms are only part of the decision. The draw schedule, inspection requirements, and timing of each release can affect the whole job.
A weekly cost review also helps. If actual spending starts drifting away from the budget, the investor can respond before the gap gets large. That's one of the quieter short term financing advantages, it gives the project structure instead of forcing the investor to improvise after closing.
4. Bridge and Transitional Financing
Bridge financing fits a deal that needs capital now, while the long-term loan or sale is still ahead. Transitional financing serves a similar role during the hold period, when an investor is improving the asset, leasing it up, or getting it ready for refinance or disposition. The benefit is time. The trade-off is carrying a higher-cost loan while the exit is still under construction.
A buyer may need to close on a new rental before the current property sells. A bridge loan can cover that gap until the sale proceeds arrive. For a fuller look at the trade-offs, see this analysis of bridge loan pros and cons. Another investor may buy a building that needs leasing and light improvements before it qualifies for longer-term debt. In that case, the bridge loan keeps the project moving, but only if the investor can show how and when the property will stabilize.
The exit plan has to be specific. Quick Lending's transitional loans are intended to support defined exit strategies, subject to review and approval. A borrower should spell out the sale, refinance, or stabilization milestone, and include a backup if the first path takes longer than expected. If the timetable is vague, the bridge loan can become a delay instead of a solution.
Bridge lending volume keeps climbing even when exits weaken. Reporting citing Fitch data put CRE CLO bridge volume at $31.6 billion through August 2026, with modified loans up 68.6% from the end of 2025 to nearly $4 billion. That pattern suggests flexibility can hide maturity pressure when the exit is soft bridge loan market report.
For a multifamily investor, the decision point may be whether leasing vacant units before refinancing will create enough income for the next loan. For a landlord with a property in transition, it may be whether unit upgrades and a cleaner rent roll are enough to support a longer-term exit. The advantage is real only when the bridge is crossing to a financeable outcome.
5. Flexibility Through Asset-Based Underwriting
Short-term lenders often care more about the asset and the project than a traditional consumer mortgage lender does. That asset-based focus can be a major advantage for investors whose income is variable, who own several properties, or who are self-employed. It gives the property and business plan more weight in the review.
Why this matters to working investors
A self-employed investor may have strong project experience but irregular tax-return income. Another investor may already own multiple rentals and want to keep conventional loans reserved for other holdings. In both cases, short-term asset-based underwriting can fit better than a home-loan style review.
Quick Lending specializes in hard money for investment properties rather than consumer home loans, so the process stays tied to investor use cases. The exact qualification criteria are subject to review and approval, which is why preparation matters. The stronger the project file, the easier it is for the lender to understand the deal.
A solid submission package should include:
- Project summary: Purchase price, rehab budget, timeline, and exit.
- Experience evidence: Past deals, if available, and project references.
- Property support: Comparable sales and photos or inspection notes.
- Contractor input: Scope and cost estimates that match the plan.
Capital market real estate insights can help frame how investors think about borrowing, project risk, and capital use.
Practical rule: Asset-based lending is most useful when the borrower can explain the deal better than the tax return can.
That's one of the most practical short term financing advantages for real estate entrepreneurs, it can support a viable project even when the borrower's income pattern doesn't fit a standard mortgage box.
6. Local Market Knowledge and Responsive Communication
Investors working in one metro area benefit when the lender understands that market's title practices, service providers, and transaction pace. In Houston, that can matter a lot. A regional lender is more likely to understand how local neighborhoods move, how title companies handle investor deals, and where timelines tend to slow down.
Why local familiarity reduces friction
A Houston-area investor flipping homes in a particular suburb may be dealing with appraisal patterns and closing expectations that differ from another part of the city. A wholesaler with a deal in motion may need quick answers while the contract is still alive. In both situations, responsiveness helps keep the file from stalling.
Quick Lending is a Houston-area lender focused on investment real estate, and its emphasis on responsiveness during underwriting and closing is meant to reduce delays. That doesn't guarantee any particular result, but it does improve the odds that questions get answered before they become problems.
The borrower can help by introducing the title company and insurance agent early, sharing local comp data, and confirming geographic coverage before building the deal around a lender's funding. Those steps sound simple, but they cut down on handoffs and confusion.
A lender that understands local execution can also be more useful during tight deadlines. The investor doesn't just need capital, the investor needs a process that moves in sync with the contract. That's especially true when inspections, insurance, and closing coordination all have to happen at once.
7. Preserving Working Capital for Additional Projects
Using financing instead of tying up all available cash in one property can leave room for the next opportunity. That matters for investors who want reserves for repairs, holding costs, or another acquisition. The benefit is simple, liquidity stays available instead of being locked into a single deal.
Capital efficiency with a real trade-off
An investor with limited cash may finance one acquisition and keep reserves ready for another property that needs unexpected repairs. A small developer may use financing for the purchase and preserve working capital to pay contractors during construction. The short-term loan helps the investor stretch capital across more than one project.
That said, preserved cash is not free. Borrowing adds carrying costs and increases the importance of a clean exit. A loan that protects liquidity can still hurt the deal if the total cost of funds overwhelms the profit margin. That is why the investor should model financing costs, holding costs, and selling costs before committing.
A good reserve plan usually answers three questions:
- How much cash stays after closing?
- How many projects can the team realistically support?
- What happens if repairs take longer than expected?
Quick Lending's short-term structures can support that kind of planning because they're designed around the project rather than long-term balance-sheet commitments. For investors who value flexibility, that can be the difference between doing one deal and keeping room for the next.
8. Clear Exit-Based Planning and Defined Project Structure
Short-term financing works best when the deal already has a beginning, middle, and end. Acquisition comes first, then improvement or stabilization, then sale or refinance. That structure makes it easier to plan cash flow and make decisions while the project is moving.
Why a defined exit keeps the loan useful
When a lender sets expectations early, the borrower knows what documents matter, what milestones must be met, and what changes could trigger another review. That clarity helps the investor budget more accurately and avoid surprises later. Quick Lending emphasizes clear process orientation and setting expectations at the outset, which supports better planning for the investor.
A flipper might map out purchase, permitting, renovation, listing, and sale milestones, then compare actual progress against that plan each month. A landlord may set occupancy and expense targets before acquisition so a refinance decision has a clear benchmark later. The loan term and repayment structure still vary by project, so the borrower should confirm those terms before closing.
Practical rule: The best short-term loan is one that fits the exit, not one that just gets money out the door.
The earlier advantages come together. Speed helps the investor get the property, flexibility helps the investor qualify, and capital preservation helps the investor keep moving. But none of it works well without a written exit strategy that can hold up under delay, cost overruns, or a slower-than-planned sale.
Short-Term Financing Advantages: 8-Point Comparison
| Item | Implementation complexity | Resource requirements | Expected outcomes | Ideal use cases | Key advantages |
|---|---|---|---|---|---|
| Speed to Close in Time-Sensitive Transactions | Low–Moderate, streamlined property-focused underwriting but requires quick coordination | Minimal paperwork if ready; fast title/appraisal and borrower responsiveness | Faster funding decisions; improved chance to meet tight deadlines (not guaranteed) | Auctions, short option periods, competitive offers | Rapid, property-centric decisions that help meet compressed closing timelines |
| Financing Properties That Need Work | Moderate, requires credible rehab plan and cost estimates | Scope of work, contractor bids, ARV comps, contingency reserves | Ability to acquire non-bankable/distressed properties and fund repairs | Distressed, fire-damaged, or uninhabitable properties needing rehab | Enables purchase of properties conventional lenders decline; supports value-add projects |
| Purchase and Rehab Funding in One Structure | Moderate–High, coordination of purchase + draw schedules | Detailed line-item budget, timeline, draw documentation and contractor coordination | Consolidated funding for acquisition and rehab; simplified cashflow management | Fix-and-flip projects and staged renovations for resale | Single loan covers both phases, reducing administrative complexity |
| Bridge and Transitional Financing | Moderate, requires clear exit milestones and monitoring | Exit strategy, carrying cost projections, stabilization/lease-up plan | Short-term capital to bridge until sale, refinance, or stabilization | Gap financing between transactions; lease-up or stabilization periods | Fills timing gaps and supports transition to longer-term financing |
| Flexibility Through Asset-Based Underwriting | Low–Moderate, property and plan-focused evaluation instead of strict income verification | One-page project summary, comps, proof of experience, property docs | Greater access for borrowers with non-traditional income or multiple properties | Self-employed investors, portfolio owners, borrowers with irregular income | Emphasizes collateral and project viability over consumer credit profile |
| Local Market Knowledge and Responsive Communication | Low, process benefits from regional expertise and communication protocols | Local comps, title and service-provider contacts, clear points of contact | Smoother local transactions and fewer market-specific surprises | Investors active in the lender's metro area (e.g., Houston) | Faster responses, regional relationships, improved coordination with local professionals |
| Preserving Working Capital for Additional Projects | Low–Moderate, requires financial planning and oversight | Cash modeling, reserves, lender terms analysis, advisor input | Preserved liquidity to pursue multiple projects; higher leverage efficiency | Portfolio builders, investors with limited cash seeking scale | Frees cash for renovations/reserves and supports more concurrent deals |
| Clear Exit-Based Planning and Defined Project Structure | Moderate, needs documented milestones and lender alignment | Project timeline, milestone metrics, team coordination, documentation | Disciplined execution and predictable repayment tied to exit | Flips, refinance-planned projects, rehabilitation with defined sale timeline | Provides a roadmap for budgeting, milestone tracking, and lender expectations |
Turning Short Term Financing Into a Clear Plan
The core takeaway is straightforward, short term financing advantages are strongest when speed, flexibility, bridge capital, and working-capital preservation all support a defined project with a realistic exit. That means the investor should not treat short-term debt as a shortcut. It works best as a tool for a specific deal stage, whether that stage is contract, renovation, stabilization, or refinance.
Before borrowing, the investor should write a timeline, budget, and exit strategy, then review the plan with a licensed contractor, accountant, financial advisor, or other appropriate professional. The key test is simple, does the loan help the property move from one phase to the next without creating a bigger problem later? If the answer is yes, short-term financing may be a useful fit. If the exit is weak, the loan may only delay the underlying issue.
Quick Lending, LLC offers short-term financing for Houston-area real estate investors who need to move quickly on acquisitions, rehab projects, or transition periods. A quote request can help compare structure and fit, but it does not guarantee approval, funding, or any closing timeline. Investors who want to see whether the structure fits their project can request a Quick Quote at quicklending.com and discuss the deal with the team.
Quick Lending, LLC helps Houston-area investors use short-term financing to move from contract to closing, through rehab, and toward a planned exit. For fix-and-flip projects, bridge needs, or distressed acquisitions, the team can review the property and the project structure with speed in mind. Visit Quicklending LLC to request a quote and see whether the financing fits the deal.